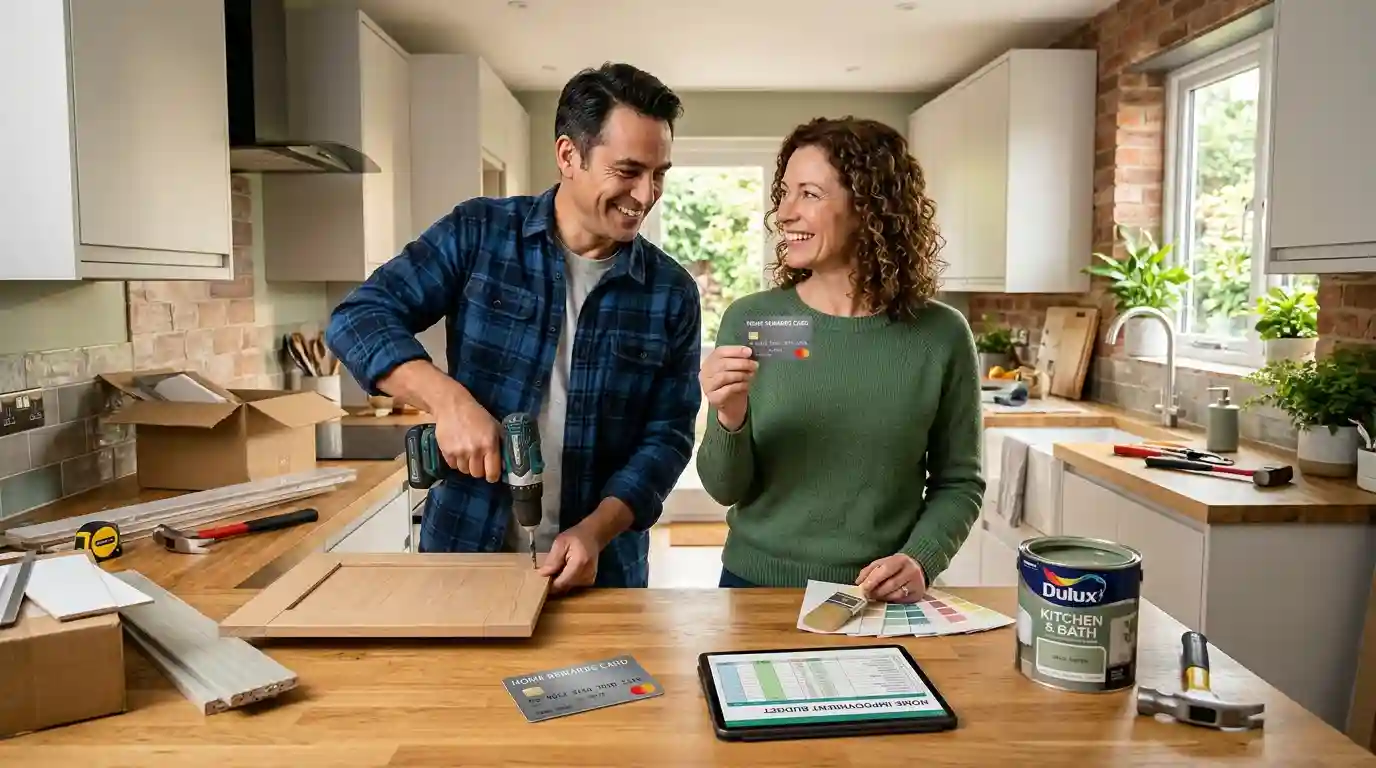
Credit cards for home improvement can help homeowners pay for renovations, repairs, appliances, and building supplies. Cards with introductory 0% APR offers may provide time to repay purchases without interest during the promotional period. Cash-back cards can also reward eligible spending. Compare fees, interest rates, credit limits, and repayment terms before choosing a card.
Key Takeaways
- 0% introductory APR cards may help finance renovations without purchase interest during a limited promotional period.
- Cash-back rewards cards can return a percentage of eligible spending on materials, appliances, and other purchases.
- Store credit cards may offer discounts or special financing but can have restrictive terms.
- Your repayment plan matters. Carrying a balance after a promotional offer ends can become expensive.
- Compare alternatives. Personal loans, home equity loans, and HELOCs may suit larger projects better than credit cards.
Credit Cards for Home Improvement
Introduction
Home improvement projects can range from replacing a broken water heater to remodeling an entire kitchen. Whether you need paint, flooring, new appliances, or professional labor, the right payment method can help you manage costs without putting too much pressure on your budget.
Credit cards for home improvement offer different benefits depending on how you plan to use them. Some provide introductory 0% annual percentage rates (APR), while others offer cash back, store discounts, or rewards on everyday purchases. However, a card that works well for a small repair may not be suitable for a large renovation.
The key is to compare financing costs, promotional terms, rewards, and repayment options before applying. This guide explains 10 credit card options and financing approaches, how to choose one, common mistakes to avoid, and when a personal loan or home equity option may make more sense.
What Does “Credit Cards for Home Improvement” Mean?
Credit cards for home improvement are credit cards people use to pay for home repairs, remodeling, renovation materials, appliances, and related expenses. They may be general-purpose cards, retailer cards, or cards with promotional financing.
Homeowners often use them to spread payments over time, earn rewards, or take advantage of discounts. The best choice depends on the project cost, available credit, interest rate, and the amount you can repay each month.
A credit card is not automatically an inexpensive way to finance a renovation. If you carry a balance after a promotional period, interest can add substantially to your total cost.
Why Choose a Credit Card for Home Improvement?
The right card can make project expenses easier to track and may provide useful savings. Consider these potential benefits:
- Earn rewards: Receive cash back or points on eligible purchases.
- Manage short-term costs: Spread payments across billing cycles.
- Use introductory APR offers: Qualifying purchases may receive a temporary 0% APR.
- Access retailer benefits: Certain store cards offer discounts or special financing.
- Track spending: Review materials and other expenses on monthly statements.
Before applying, make sure the card’s benefits outweigh its fees and potential interest costs.
10 Best Credit Card Options for Home Improvement
These are 10 card types and financing approaches to compare, rather than a ranking of individual cards. Current offers and approval requirements can change, so review each issuer’s terms before applying.
1. Credit Cards With a 0% Introductory APR
Meaning: These cards charge no interest on qualifying purchases during a specified introductory period. After that period, the standard purchase APR generally applies to any remaining balance.
Best For:
Planned renovations with a clear repayment schedule.
Example 1:
You charge $3,000 in eligible flooring expenses to a card with a 15-month 0% purchase APR.
Example 2:
You divide a $4,500 appliance purchase into 15 planned monthly payments of $300.
Quick Tip:
Aim to repay the full balance before the promotional period ends. Continue making at least the required minimum payments on time.
2. Flat-Rate Cash-Back Credit Cards
Meaning:
These cards earn a set percentage of cash back on eligible purchases. The reward rate usually stays the same regardless of where you buy materials.
Best For:
Homeowners who purchase supplies from several stores.
Example 1:
You earn 2% cash back on eligible purchases totaling $1,500, receiving $30 in rewards.
Example 2:
You use one card for paint, lighting, tools, and plumbing supplies from different retailers.
Quick Tip:
Check whether the card has an annual fee and whether rewards are reduced or limited for particular transactions.
3. Home Improvement Store Credit Cards
Meaning:
Retailer credit cards are designed for purchases at a particular home improvement chain. They may provide store discounts, promotional financing, or other shopping benefits.
Best For:
Projects with most material purchases at one retailer.
Example 1:
You use a store card to purchase cabinets and hardware for a kitchen update.
Example 2:
You compare a retailer’s financing offer with a general-purpose card before purchasing a new washer and dryer.
Quick Tip:
Read the promotional terms carefully. Some offers use deferred interest, which can add interest dating back to the purchase if you fail to pay the promotional balance in full by the deadline. Consumer Financial Protection Bureau+1
4. Credit Cards With Rotating Bonus Categories
Meaning: These cards offer higher rewards in selected spending categories during certain periods. The categories and activation requirements depend on the issuer.
Best For: Homeowners whose purchases match an available bonus category.
Example 1: You activate a quarterly offer that includes eligible purchases at a participating home improvement store.
Example 2: You schedule a planned supply purchase during a period when the store qualifies for bonus rewards.
Quick Tip: Confirm that the retailer and transaction qualify. A purchase does not necessarily earn bonus rewards simply because it relates to home improvement.
5. Credit Cards With Customizable Bonus Categories
Meaning: Some cards let you select an eligible spending category or automatically reward your highest eligible spending category. Category choices and reward caps vary.
Best For: Homeowners who can concentrate eligible spending in a qualifying category.
Example 1: You choose a qualifying home improvement category before buying supplies for a bathroom renovation.
Example 2: You use a card’s eligible online shopping category for qualifying online purchases of fixtures and tools.
Quick Tip: Check monthly or quarterly reward limits. Spending above the limit may earn a lower rate.
6. General-Purpose Rewards Credit Cards
Meaning: These cards earn points, miles, or other rewards on eligible purchases. Their value depends on how you redeem those rewards.
Best For: People who already understand and use a card’s rewards program.
Example 1: You earn points on a new refrigerator purchase and later redeem them under the issuer’s rewards rules.
Example 2: You use a rewards card for eligible renovation purchases and everyday expenses that you can repay in full.
Quick Tip: Compare the real value of the rewards with any annual fee and interest charges. Rewards rarely justify carrying expensive debt.
7. Credit Cards With Purchase Protection
Meaning: Some credit cards include benefits that may cover certain eligible purchases against specified damage, theft, or other covered events for a limited period.
Best For: Eligible purchases of appliances, tools, and household equipment.
Example 1: You buy a new power tool and keep the receipt in case you need to submit a covered claim.
Example 2: You purchase a qualifying appliance and review the card’s purchase protection terms before installation.
Quick Tip: Read the exclusions, coverage limits, claim deadlines, and documentation requirements. Coverage is not guaranteed for every purchase.
8. Business Credit Cards for Contractors
Meaning: Business credit cards help eligible business owners manage expenses related to their trade or company. Depending on the card, they may offer expense tracking, employee cards, or business rewards.
Best For: Contractors and other eligible business owners buying supplies for business projects.
Example 1: A contractor uses a business card to separate job-related tool purchases from personal expenses.
Example 2: A remodeling business tracks eligible lumber, equipment, and supply purchases through monthly statements.
Quick Tip: Use business credit for legitimate business expenses and review the card’s eligibility requirements. A business card is not automatically the right choice for a homeowner’s personal renovation.
9. Credit Cards With Long Introductory Financing Periods
Meaning: Some cards provide extended 0% introductory APR periods on eligible purchases. The exact duration and qualifying terms vary by offer.
Best For: Larger projects that can be repaid within the promotional period.
Example 1: You plan a $6,000 renovation and compare cards offering different introductory purchase APR periods.
Example 2: You estimate monthly payments before buying new windows to confirm that the repayment schedule fits your budget.
Quick Tip: A longer promotional period may help, but only if the credit limit covers the purchase and you can meet the repayment schedule. A long offer does not make an unaffordable project affordable.
10. Low-Interest Credit Cards
Meaning: These cards have a relatively low ongoing purchase APR compared with the alternatives available to a particular applicant. Actual rates depend on the issuer and creditworthiness.
Best For: People who may need to carry a balance beyond one billing cycle.
Example 1: You compare available purchase APRs before charging an unexpected furnace repair.
Example 2: You choose a card with a lower ongoing rate because your planned payments may extend beyond a promotional period.
Quick Tip: Compare the actual APR offered to you, not just the lowest rate advertised. If you expect to carry substantial renovation debt for a long time, compare personal loans and other financing options too.
Comparison Table
| Credit card option | Best used for | Typical benefit |
|---|---|---|
| 0% introductory APR card | Planned renovations | Temporary interest savings |
| Flat-rate cash-back card | Mixed supply purchases | Consistent cash back |
| Home improvement store card | Purchases at one retailer | Store-specific benefits |
| Rotating bonus card | Eligible seasonal purchases | Higher rewards in selected categories |
| Customizable bonus card | Concentrated eligible spending | Flexible rewards |
| General-purpose rewards card | Everyday renovation spending | Points, miles, or cash back |
| Purchase protection card | Eligible appliances and tools | Potential purchase coverage |
| Business credit card | Contractor business expenses | Business expense tracking |
| Long introductory APR card | Larger planned projects | More time before standard APR begins |
| Low-interest credit card | Balances that may take longer to repay | Lower borrowing costs if the offered APR is competitive |
Benefits vary by card, issuer, purchase type, and current offer. Some options overlap, so compare the actual card terms rather than relying on the category name.
Common Mistakes When Choosing Home Improvement Credit Cards
1. Ignoring the regular APR. A 0% offer can look attractive, but the standard rate matters if you still owe money when the promotion ends.
2. Confusing 0% APR with deferred interest. With a standard 0% introductory APR offer, interest generally begins on the remaining balance after the promotion. With deferred interest, missing the payoff deadline can trigger previously deferred interest under the offer’s terms. Consumer Financial Protection Bureau
3. Assuming contractors accept credit cards. Some contractors accept cards, while others prefer checks, bank transfers, or other payment methods. Ask about processing fees before paying.
4. Overspending to earn rewards. Cash back does not make an unnecessary purchase worthwhile. Spending more than planned can cost far more than the rewards you earn.
5. Choosing a card without calculating monthly payments. Divide your planned borrowing by the number of months available for repayment, then add a safety margin for unexpected expenses. Remember that new purchases or project overruns can increase the balance.
Frequently Asked Questions
1. What are the best credit cards for home improvement?
The best card depends on your priorities. A 0% introductory APR card may suit a renovation you can repay before the offer ends, while a cash-back card may work better for purchases you can pay off monthly. Compare annual fees, standard APRs, credit limits, rewards, and promotional terms before applying.
2. Can I use a credit card to pay for home renovations?
Yes, if your contractor or supplier accepts credit cards and your available credit covers the transaction. You can generally use a card for eligible purchases such as flooring, paint, appliances, and tools. Ask contractors about processing fees, and confirm that your card’s terms permit the transaction.
3. Is a 0% APR credit card good for home improvement?
A 0% introductory APR card can be useful if you have a reliable payoff plan and qualify for the offer. It may allow you to spread eligible purchases over several months without purchase interest during the introductory period. However, missed payments or an unpaid balance after the offer ends can increase your costs.
4. Are home improvement store credit cards worth it?
Store cards may be worthwhile if you regularly shop at one retailer and can use its discounts or financing offers. However, benefits may be limited to that store, and promotional financing may include deferred-interest conditions. Compare the store card with a general-purpose rewards card before deciding.
5. What credit score do I need for a home improvement credit card?
There is no single credit score requirement for every card. Approval depends on the issuer’s criteria, your credit history, income, existing debts, and other application details. Cards with stronger introductory offers may require better credit. Review the issuer’s stated requirements, but remember that meeting them does not guarantee approval.
6. Can I earn cash back on home improvement purchases?
Yes. Eligible purchases may earn cash back through flat-rate rewards cards, bonus-category cards, or retailer-specific programs. The amount depends on the card’s reward rate, spending limits, and transaction eligibility. For example, 2% cash back on $2,000 in eligible purchases equals $40 before considering fees or other costs.
7. Is a credit card better than a home improvement loan?
A credit card may suit smaller expenses or a renovation that qualifies for a favorable introductory APR. A personal loan may offer fixed payments and a defined repayment term, while home equity financing may provide other rates and risks. Compare the total borrowing cost, fees, repayment schedule, and consequences of missed payments.
8. Should I use a credit card for a major home renovation?
It depends on the renovation cost, your credit limit, and how quickly you can repay the debt. Charging a large project to a card with a high ongoing APR can become expensive. For major renovations, compare credit cards with personal loans, home equity loans, and HELOCs before borrowing.
Conclusion
Choosing among credit cards for home improvement starts with understanding your project’s cost and your ability to repay what you borrow. A 0% introductory APR card may help with planned renovations, while a cash-back card can reward eligible purchases when you pay your balance in full. Store cards may provide useful discounts, but their financing terms deserve careful attention.
Before applying, compare the regular APR, promotional period, annual fee, credit limit, and any transaction fees. Calculate your monthly payments and leave room in your budget for unexpected repairs. If your project requires substantial borrowing, compare credit cards with personal loans and home equity financing.
The best card is not necessarily the one with the biggest reward or longest promotional offer. It is the one that fits your budget, offers useful benefits, and lets you repay the balance without taking on costly debt.

I am a fan of famous American author James Patterson and I love sharing interesting information about him on my website namezvibez.com. I am inspired by his incredible storytelling and the many bestselling books he has written. I am creating content to help readers quickly learn about his life, career, and achievements in a simple and engaging way. On namezvibez.com, I share short and useful details about popular authors and personalities. ✍️📚